

How to Get a Home Loan or Construction Loan in Vadodara 2026
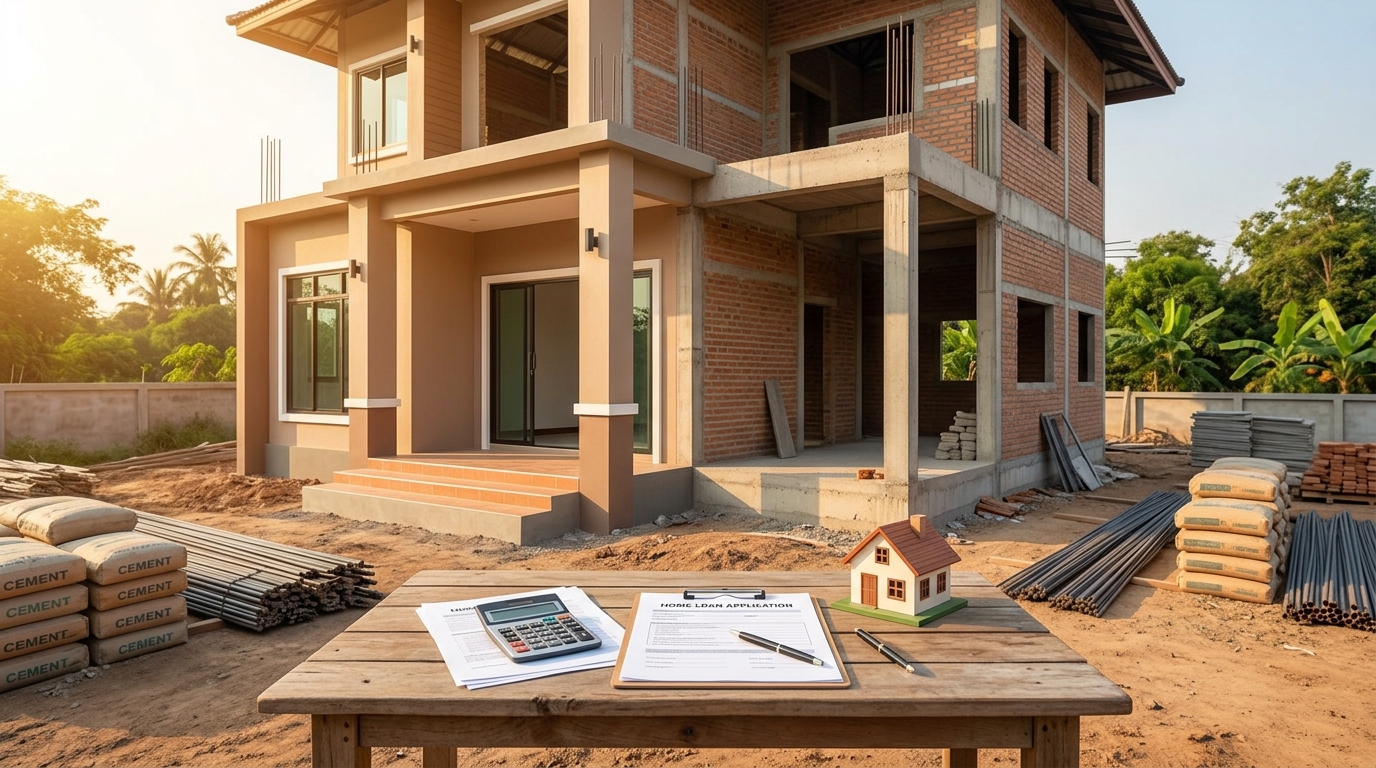
If you own a plot in Gotri or Manjalpur and you’re ready to start building but your savings fall short, a construction loan Vadodara is likely the most practical path forward. Many Vadodara families are sitting on registered land but don’t know how to unlock bank financing for ghar bandhkam — and that gap costs them months of delay. This guide walks you through every step of the process in plain language, with real numbers for the 2026 market. If you need a builder who can provide the cost estimates and documentation that banks actually accept, Book a Free Site Visit with JKC Buildcon Services today.
2026 Cost Guide: Home Loan & Construction Costs in Vadodara
Before approaching any bank, you need a realistic picture of what construction actually costs in Vadodara in 2026. Material costs in Gujarat have risen 12–18% since 2022, and lenders require a certified cost estimate before sanctioning any construction loan. The table below reflects current market rates for residential construction in Vadodara, combining material and labor costs.
| Construction Type | Low Budget (₹/sq ft) | Mid Range (₹/sq ft) | Premium (₹/sq ft) |
|---|---|---|---|
| Ground Floor Construction (RCC) | ₹1,400 – ₹1,700 | ₹1,800 – ₹2,200 | ₹2,400 – ₹3,200 |
| Multi-Floor Bungalow (G+1 / G+2) | ₹1,600 – ₹1,900 | ₹2,000 – ₹2,500 | ₹2,600 – ₹3,500 |
| Floor Extension / Additional Floor | ₹1,200 – ₹1,500 | ₹1,600 – ₹2,000 | ₹2,100 – ₹2,800 |
| Full Home Renovation (makaan renovation) | ₹600 – ₹900 | ₹950 – ₹1,400 | ₹1,500 – ₹2,200 |
| Typical Loan Processing Fees (Banks) | 0.25% – 0.50% of loan | 0.50% – 1.00% of loan | 1.00% – 1.50% of loan |
Contractor Insight: Banks typically finance 75–90% of the construction cost based on a technical valuation report. Always get your cost estimate from a registered contractor — a rough verbal quote won’t be accepted by any lender in 2026.
Types of Home Loans and Construction Loans Available in Vadodara
Not all home loans are the same, and choosing the wrong type can delay your project by months. Vadodara borrowers in 2026 have access to four main financing structures depending on their situation.
Standard Home Loan
This is for purchasing a ready-built or under-construction flat or house from a registered developer. Banks disburse the amount in one shot or in tranches linked to construction stages. Interest rates in 2026 range from 8.50% to 9.75% per annum for salaried applicants.
Self-Construction Loan
This is the most relevant product if you own a plot and want to build your own home — ghar bandhkam on your own terms. The bank disburses funds in stages aligned with construction milestones (foundation, plinth, slab, finishing). You pay interest only on the disbursed amount during construction.
Plot + Construction Loan
If you’re buying a plot and building simultaneously, some banks offer a composite loan covering both. This is increasingly popular in new Vadodara townships like Waghodia Road and Tarsali. The combined LTV (Loan-to-Value) is usually capped at 75–80%.
Loan Against Property (LAP)
If you already own a property, you can mortgage it to fund construction or renovation. LAP rates in 2026 are slightly higher — 9.50% to 11.50% — but approval is faster since the asset is already established.
- Standard Home Loan: Best for buying ready property or builder flats
- Self-Construction Loan: Best for plot owners building independently
- Composite Plot + Construction Loan: Best for new township buyers
- Loan Against Property (LAP): Best for existing property owners needing funds fast
Eligibility Criteria and Documents Required
Who Qualifies?
Banks in Vadodara assess eligibility based on income stability, credit score, and property legality. A CIBIL score of 700 or above is the minimum threshold for most nationalized banks; private banks and NBFCs may accept scores as low as 650 with higher interest rates. Salaried applicants need a minimum of 2 years of employment history, while self-employed applicants need 3 years of ITR filings.
The property must have a clear title deed, valid NA (Non-Agricultural) conversion if applicable, and an approved building plan from VMC (Vadodara Municipal Corporation). Banks will not lend against unauthorized constructions or plots with disputed ownership.
- Minimum age: 21 years; Maximum age at loan maturity: 65–70 years
- Minimum monthly income: ₹25,000 (salaried) / ₹30,000 net profit (self-employed)
- CIBIL score: 700+ preferred; 650+ accepted by some NBFCs
- Property: Clear title, VMC-approved plan, NA conversion certificate where applicable
- Loan tenure: Up to 30 years for most banks in 2026
Documents Checklist
Missing even one document can stall your loan application for weeks. Prepare this checklist before walking into any bank branch in Vadodara.
- KYC: Aadhaar, PAN card, recent passport-size photographs
- Income Proof: Last 3 months’ salary slips OR last 3 years’ ITR with computation
- Bank Statements: Last 6–12 months from all active accounts
- Property Documents: Title deed, 7/12 extract, NA order, index-II, property tax receipts
- Construction Documents: VMC-approved building plan, registered architect’s drawings
- Cost Estimate: Detailed estimate from a registered contractor (this is mandatory)
- Employment Proof: Appointment letter, Form 16, or business registration certificate
Pro Tip: Get your cost estimate prepared on a contractor’s letterhead with GST number. Banks’ technical valuers cross-check this estimate before approving the loan amount. A vague or handwritten quote will be rejected outright.
Step-by-Step Process to Apply for a Construction Loan in Vadodara
The loan process for ghar bandhkam in Vadodara follows a predictable sequence once you understand it. Most delays happen because applicants approach banks without proper documentation or without an approved building plan. Follow this process in order and you’ll avoid the most common bottlenecks.
- Step 1 – Get Your Plot Documents in Order: Ensure your title deed, NA conversion, and 7/12 extract are updated and mutation is complete at the Vadodara Collector’s office. This alone can take 4–8 weeks if not done in advance.
- Step 2 – Get VMC Building Plan Approval: Submit architectural drawings to VMC for building permission. In 2026, VMC’s online portal has streamlined this, but physical follow-up is still often needed. Approval typically takes 4–10 weeks.
- Step 3 – Get a Detailed Construction Cost Estimate: Hire a registered contractor to prepare a scope-wise cost estimate. This document is mandatory for bank submission and should include material specifications, labor costs, and a construction timeline.
- Step 4 – Compare Lenders: Visit at least 3–4 banks or use a loan aggregator. Compare interest rates, processing fees, disbursement schedule, and prepayment penalties. SBI, HDFC, ICICI, and LIC Housing Finance are all active in Vadodara in 2026.
- Step 5 – Submit Application and Await Technical Valuation: The bank sends a technical valuer to inspect your plot and verify the construction plan. This valuation determines the actual loan amount you’ll receive.
- Step 6 – Loan Sanction and Agreement Signing: Once sanctioned, review the loan agreement carefully — check the disbursement schedule, interest rate type (fixed vs floating), and foreclosure charges.
- Step 7 – Stage-Wise Disbursement During Construction: Funds are released in 4–6 tranches as construction progresses. The bank sends an inspector before each disbursement to verify stage completion.
Pro Tip: Choose a contractor who is familiar with bank disbursement schedules. Delays in completing each construction stage on time can hold up your next loan tranche — and your entire project timeline suffers.
Common Mistakes Homeowners Make When Applying
After working with hundreds of Vadodara families on ghar sudharo and new construction projects, the same four mistakes appear again and again. These are avoidable errors that cost applicants weeks of delay and sometimes significant money.
Mistake 1: Applying Before Getting VMC Plan Approval
Many homeowners approach banks before their building plan is approved by VMC. Banks cannot process a self-construction loan without a sanctioned plan — this is non-negotiable. Get the VMC approval first, then approach the bank.
Mistake 2: Using an Unregistered or Informal Contractor’s Estimate
A cost estimate from an unlicensed contractor or a handwritten quote will be rejected by the bank’s technical team. The estimate must come from a registered contractor with a valid GST number and professional letterhead. Banks in 2026 are stricter about this than ever.
Mistake 3: Underestimating the Total Project Cost
Homeowners often understate costs hoping to show a lower loan requirement. This backfires when actual construction costs exceed the sanctioned loan amount mid-project. Always include a 10–15% contingency buffer in your estimate.
Mistake 4: Not Comparing Disbursement Schedules Across Lenders
Different banks release construction loan tranches at different stages. A bank that releases funds only at 5 stages versus one that releases at 7 stages can significantly affect your cash flow. Always ask for the disbursement schedule in writing before signing.
- Never apply before VMC plan approval is in hand
- Always use a GST-registered contractor for cost estimates
- Add 10–15% contingency to your total project cost
- Compare disbursement schedules — not just interest rates
- Check prepayment and foreclosure charges before signing
Which Banks and NBFCs Are Best for Construction Loans in Vadodara?
Vadodara has a mature banking ecosystem with strong presence from both public sector banks and private lenders. In 2026, the following institutions are actively offering competitive self-construction and home loan products in the Vadodara market.
| Lender | Interest Rate (2026) | Max LTV | Best For |
|---|---|---|---|
| SBI | 8.50% – 9.15% | 90% | Salaried, government employees |
| HDFC Bank | 8.70% – 9.50% | 80% | Self-employed, faster processing |
| ICICI Bank | 8.75% – 9.60% | 80% | Digital-first applicants, NRIs |
| LIC Housing Finance | 8.65% – 9.40% | 85% | Long-tenure, lower EMI preference |
| Bank of Baroda | 8.55% – 9.25% | 85% | Local applicants, Vadodara HQ advantage |
| Bajaj Housing Finance (NBFC) | 9.50% – 11.00% | 75% | Lower CIBIL scores, faster approval |
Note that Bank of Baroda is headquartered in Vadodara and has a strong local presence — their branch managers often have more flexibility on case-by-case decisions for Vadodara-based applicants. Always negotiate the processing fee; most banks will waive or reduce it for strong profiles.
Pro Tip: If your CIBIL score is below 700, work on clearing outstanding dues for 6 months before applying. Even a 30-point improvement can move you from NBFC rates (10.5%) to nationalized bank rates (8.75%) — saving lakhs over a 20-year tenure.
How to Choose the Right Contractor in Vadodara
Your contractor is not just the person who builds your home — they are a critical part of your loan approval process. Banks require contractor-issued cost estimates, and their disbursement inspectors verify the work your contractor completes at each stage. Choosing the wrong contractor can delay disbursements, inflate costs, and create legal complications with the bank.
Here are six practical criteria to vet any contractor before signing a construction agreement in Vadodara in 2026.
- GST Registration and Legal Standing: Any contractor providing cost estimates for bank submission must have a valid GST number. Ask for their GSTIN and verify it on the GST portal. An unregistered contractor’s estimate will be rejected by every bank in Vadodara.
- Experience with Bank Disbursement Projects: Ask specifically whether the contractor has worked on bank-financed construction projects before. They should understand how stage-wise disbursement works and be able to plan construction milestones accordingly.
- Transparent Written Quotation: A professional contractor will provide a detailed, itemized quotation — not a lump-sum figure. The quote should break down civil work, materials, labor, finishing, and contingency separately.
- Verifiable Past Projects in Vadodara: Ask for at least 3 completed project references in Vadodara. Visit at least one site in person or speak to the homeowner directly. Look for projects similar in scale to yours.
- Clarity on Timeline and Penalty Clauses: A reliable contractor will agree to a construction timeline in writing and accept reasonable penalty clauses for delays. Contractors who resist written timelines are a red flag.
- Post-Construction Support: Ask about defect liability periods and what support they provide after handover. Reputable firms like JKC Buildcon Services offer post-completion support as standard — not as an extra charge.
JKC Buildcon Services has been working with Vadodara homeowners and their bank-financed construction projects for over 25 years. Their documentation — cost estimates, construction schedules, and material specifications — is accepted by all major banks operating in Vadodara. To get a contractor-verified cost estimate that your bank will accept, schedule your free site visit today.
- Verify GST registration before accepting any cost estimate
- Confirm experience with stage-wise bank disbursement projects
- Insist on an itemized written quotation — not a verbal or lump-sum figure
- Visit at least one completed project in Vadodara personally
- Get construction timeline and penalty clauses in writing
- Ask about post-handover defect liability period
Frequently Asked Questions
Can I get a construction loan in Vadodara if I already own the plot?
Yes — owning a plot outright actually strengthens your loan application significantly. Banks treat a plot with clear title as collateral, which reduces their risk. You will need to submit the original title deed, 7/12 extract, NA order, and a VMC-approved building plan along with your income documents. The bank will sanction the loan based on the construction cost estimate provided by your registered contractor, not the plot value. Most banks in Vadodara in 2026 will finance 75–90% of the construction cost in this scenario.
How is a construction loan different from a regular home loan in Vadodara?
A regular home loan is disbursed in one or two payments when you buy a ready or near-ready property. A construction loan Vadodara is disbursed in 4–7 tranches, each released after a bank inspector verifies that the corresponding construction stage has been completed. During the construction phase, you pay only interest on the disbursed amount — the full EMI begins only after complete disbursement. This stage-wise structure means your cash flow is tied directly to your contractor’s on-site progress, which is why choosing a reliable contractor matters so much.
What is the maximum loan amount I can get for building a house in Vadodara in 2026?
The maximum loan amount depends on two factors: your repayment capacity (based on income) and the technical valuation of your construction project. Banks typically lend up to 75–90% of the construction cost as assessed by their technical valuer — not necessarily what your contractor quotes. Most salaried applicants in Vadodara with a monthly income of ₹60,000–₹80,000 can qualify for loans of ₹40–60 lakhs in 2026. Self-employed applicants are assessed on net profit, not gross turnover, so accurate ITR filing is critical.
How long does it take to get a construction loan approved in Vadodara?
From the time you submit a complete application with all documents, most nationalized banks take 15–30 working days for sanction. Private banks and NBFCs can be faster — sometimes 7–15 working days. However, the biggest delays are typically pre-application: getting VMC plan approval (4–10 weeks), getting the property title clear (variable), and preparing the contractor cost estimate. If you have all documents ready before approaching the bank, the total timeline from application to first disbursement is typically 4–8 weeks.
Do I need a floor extension loan separately or can it be covered under a construction loan?
A floor extension Vadodara — adding a new floor to an existing house — can be financed through a home improvement loan or a top-up loan if you already have a running home loan. If you don’t have an existing loan, banks treat it as a self-construction loan on an existing property. You will need a structural stability certificate from a registered civil engineer confirming the existing structure can bear the additional load, along with VMC permission for the vertical extension. JKC Buildcon Services regularly prepares the technical documentation needed for such loans in Vadodara.
Conclusion
Getting a construction loan Vadodara in 2026 is absolutely achievable — but it requires preparation, the right documentation, and a contractor who understands the banking process as well as the construction process. The families who face delays are almost always those who approach banks before their VMC approvals are in place, or those who work with contractors who can’t produce bank-acceptable documentation.
JKC Buildcon Services, with 25+ years of experience in Vadodara’s residential construction market, has helped hundreds of homeowners navigate exactly this process — from preparing bank-ready cost estimates to completing construction on schedule so disbursement tranches arrive without delays. Whether you’re planning new ghar bandhkam, a floor extension, or a full makaan renovation, having the right contractor on your side from day one makes the entire loan process smoother.
Don’t wait until your loan is sanctioned to find a contractor — get your cost estimate and construction plan in order first, and the bank approval will follow much faster. get a free on-site consultation with JKC Buildcon Services and walk into your bank with a professional, bank-ready construction estimate in hand.